AGE Polymer Weekly Review
24–30 August 2026
Previous Week Review: 17–21 August 2026 New Week Outlook: 24–30 August 2026 Data Cut-off: 24 August 2026
Market Overview
Global polymer markets enter the new week with stronger upstream cost support but uneven downstream demand.
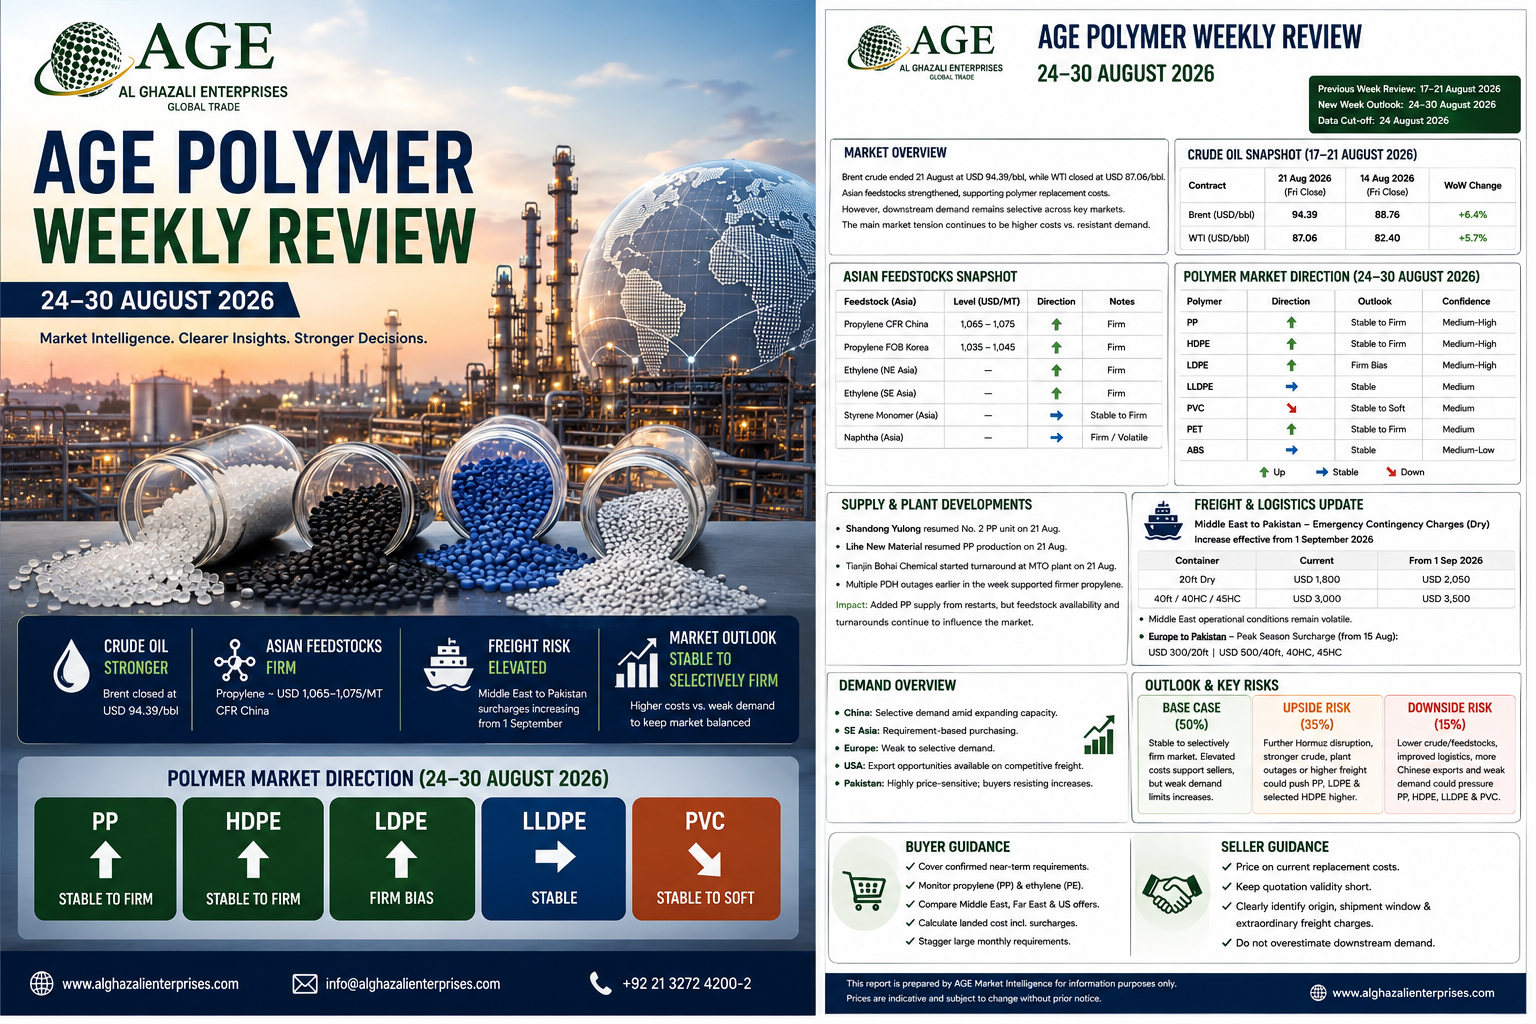
Brent crude ended 21 August at approximately USD 94.39/bbl, while WTI closed around USD 87.06/bbl. Asian petrochemical feedstocks also strengthened, increasing replacement-cost pressure across parts of the PP and PE chains.
However, polymer demand remains selective across several major consuming markets. The key market tension is therefore:
Higher upstream and logistics costs versus resistant downstream buyers.
Feedstock Watch
Asian propylene strengthened during the previous week, with CFR China indications around USD 1,065–1,075/MT.
Ethylene also showed a firm Asian trend, providing additional cost support to polyethylene producers.
Energy and freight volatility mean buyers should monitor the entire cost chain rather than crude oil alone:
Crude → Naphtha → Olefins → Polymer Resin → Freight → Landed Cost
Polymer Direction
| Product | AGE Outlook |
|---|---|
| PP | Stable to Firm |
| HDPE | Stable to Firm |
| LDPE | Firm Bias |
| LLDPE | Stable |
| PVC | Stable to Soft |
| PET | Stable to Firm |
| ABS | Stable |
Far East Asian HDPE strengthened during the previous week, while Pakistan indications remained comparatively stable.
This suggests rising Asian replacement costs are encountering significant buyer resistance in South Asia.
Supply & Plant Watch
Chinese PP availability received support from selected plant restarts during the previous week, while changes in MTO and PDH operating rates continued to affect olefin availability.
The market therefore does not currently indicate a broad polymer shortage.
Instead, producers face a combination of higher energy costs, firmer feedstocks and more expensive logistics.
Demand
China: Selective and cautious amid expanding domestic capacity.
Southeast Asia: Primarily requirement-based purchasing.
Europe: Weak to selective demand.
United States: Export opportunities remain possible where freight economics are competitive.
Pakistan: Highly price-sensitive, with buyers resisting increases despite higher international replacement costs.
Freight & Logistics
Middle East-to-Pakistan logistics remain an important risk.
Higher emergency contingency costs scheduled from 1 September 2026 could further increase the landed cost of Middle Eastern polymer cargoes into Pakistan.
Importers should therefore compare suppliers on total landed cost, not merely FOB resin values.
AGE Outlook | 24–30 August
Base Case — 50%
Polymer prices remain stable to selectively firm.
Elevated energy, propylene, ethylene and freight costs support sellers, while weak downstream demand limits aggressive increases.
Upside Risk — 35%
Further Middle East disruption, stronger crude, additional petrochemical outages or higher freight costs could push PP, LDPE and selected HDPE grades higher.
Downside Risk — 15%
Lower crude and feedstocks, improving Middle East logistics, increased Chinese exports and continued weak downstream demand could pressure commodity PP, HDPE, LLDPE and PVC.
Buyer Guidance
Buyers should cover confirmed near-term requirements while avoiding excessive speculative inventory.
Monitor propylene before major PP purchases and ethylene before PE purchases. Compare Middle East, Far East and US origins on a landed-cost basis and stagger large monthly requirements where possible.
Seller Guidance
Sellers should price from current replacement costs rather than historical inventory costs.
Quotation validity should remain short during volatile markets, and origin, shipment window and extraordinary freight charges should be clearly identified.
AGE Market View
AGE expects the polymer market during 24–30 August 2026 to remain stable to selectively firm rather than broadly bullish.
PP and LDPE carry comparatively stronger upside sensitivity. HDPE remains supported but faces buyer resistance. LLDPE is more balanced, while PVC retains the softer underlying structure.
The major variables to watch this week are crude oil, Asian olefins, Middle East logistics, plant operating rates and Chinese polymer availability.
AGE Polymer Weekly Review
Prices referenced in this review are market indications where applicable and should not be interpreted as firm executable offers.