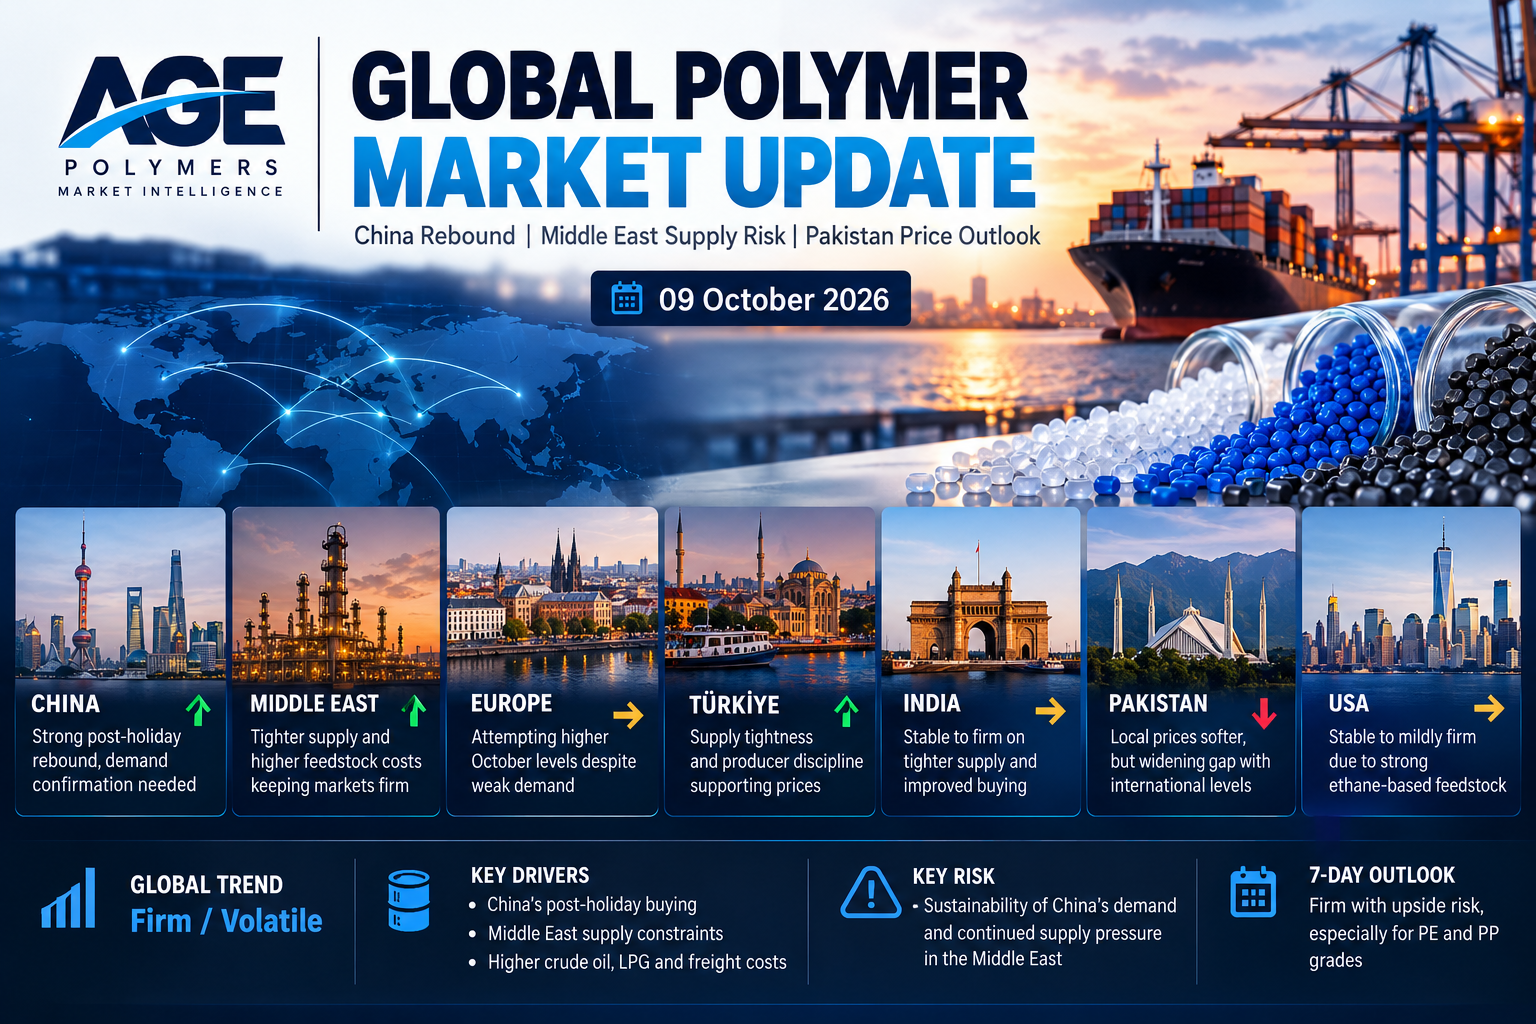
Global polymer markets are entering a firmer phase as China reopens strongly after Golden Week and Middle East feedstock, freight and supply risks continue to support higher replacement costs.
China’s PE and PP markets have shown a sharp rebound, supported by stronger futures and renewed buying activity, although the sustainability of this rally will depend on real downstream demand over the coming days. In the Middle East, higher crude oil, LPG costs and restricted availability are keeping polymer offers firm, while Türkiye and India also remain supported by tighter supply and producer discipline.
Europe is attempting higher October levels despite weak industrial demand, while the US market remains relatively stable due to its stronger ethane-based feedstock position.
Pakistan continues to move differently from most international markets. Local Karachi PE and PP prices remain under pressure, particularly in LDPE, while international South Asia replacement costs are firmer. This widening gap increases the risk that selected Pakistan grades may stabilize or rebound once cheaper local stocks are absorbed.
AGE Market View: Global polymer sentiment is firm and volatile. China and Middle East developments remain the main upside drivers, while weak downstream demand is still the biggest risk to a sustained rally.